Publisher
d’Escrivan
Eléonore
Valenciennes, France
Hosting
OVH
2 rue Kellermann -
59100 Roubaix -
France
Contacts


World 2:Repairability as a creditcriterion, under carbon card
Presentation
In 2050, every object in a household is recorded, from purchase
to repairs, in a State registry tied to the European digital product passport. This registry feeds an individual carbon score that banks and insurers use to set interest rates and premiums,
without ever seeing what it is made of.
Story
In 2027, the European ecodesign regulation comes into force, sector by sector. Every product receives a digital product passport
that records its composition, its lifespan and its repairs. The idea
is presented as a measure of environmental traceability, a tool against greenwashing. Above all, it creates, object by object,
a reliable history: the raw material for everything that follows.
In 2033, several pilot cities experiment with a voluntary individual carbon card, whose score is calculated by a public registry
that aggregates the passports of the objects each person declares.
It is described as a simple local experiment on data that already exists. Six years later, in 2039, the card becomes mandatory across the country. The score is used to steer climate policy and to produce national statistics. For five years, the score settles into everyday habits without anyone imagining it could be used for anything else.
In 2044, after several climate events that were costly for insurers,
a law allows banks and insurers to consult the score, never
the registry's detail, in order to adjust loan rates and premiums.
The extension seems logical: the score has been legitimate
and accepted for five years, and the initial opposition has dissolved in the meantime.
In 2047, the score is split into three: general carbon footprint, ability to repair (declared skills, disposable income to pay a repairer)
and repair habits (number of objects owned, their age, repairs actually carried out). The compensation rule fits in a slogan:
“One goes out, one comes in.” Buying a new object without having given up the equivalent weighs fully on the quota; giving it up
before buying a new one cancels the effect. Lending and borrowing are not forbidden and have even become commonplace:
in neighbourhoods, the library of things has replaced buying the drill you use twice a year. However, not declaring an object you own
is penalised, and falsifying a self-repair in an object's passport
has become a separate offence. Insurers have added repairability clauses to home insurance contracts.
Rachid practises a trade that did not exist ten years ago: carbon score adviser. Authorised by the State to consult the registry's detail with his clients' consent, he is the only private professional who sees what the banks cannot see. He helps households improve their repair habits or, as he sometimes admits in hushed tones, present
their data in the most favourable light. He knows the difference between optimising a score and genuinely reducing a household's footprint, but his authorisation, which can be revoked, depends
on the administration.
In 2049, an entire generation has been born with the score. It has never known credit or insurance without it. The debate over whether it is justified fades for lack of any memory of another system,
and the authorities see in this the proof of successful
social acceptability.
On a Tuesday in 2050, Léa and Tom book the drill
from their neighbourhood's library of things for Saturday. Borrowing rather than buying has become a reflex. Opening the app that tracks their repairs, Léa sees that their score has dropped by four points. No explanation, only the number. She calls the bank: the adviser sees the result, never the detail, and suggests they contact
the administration. Tom thinks back to the toaster bought in March: the site had shown the impact on the quota and offered to take back the old one, they had ordered anyway, and the old one is still
in the cupboard. In the bedroom, their six-year-old daughter,
who has never known credit without a score, asks if the toaster
can be repaired “so the number goes back up.”
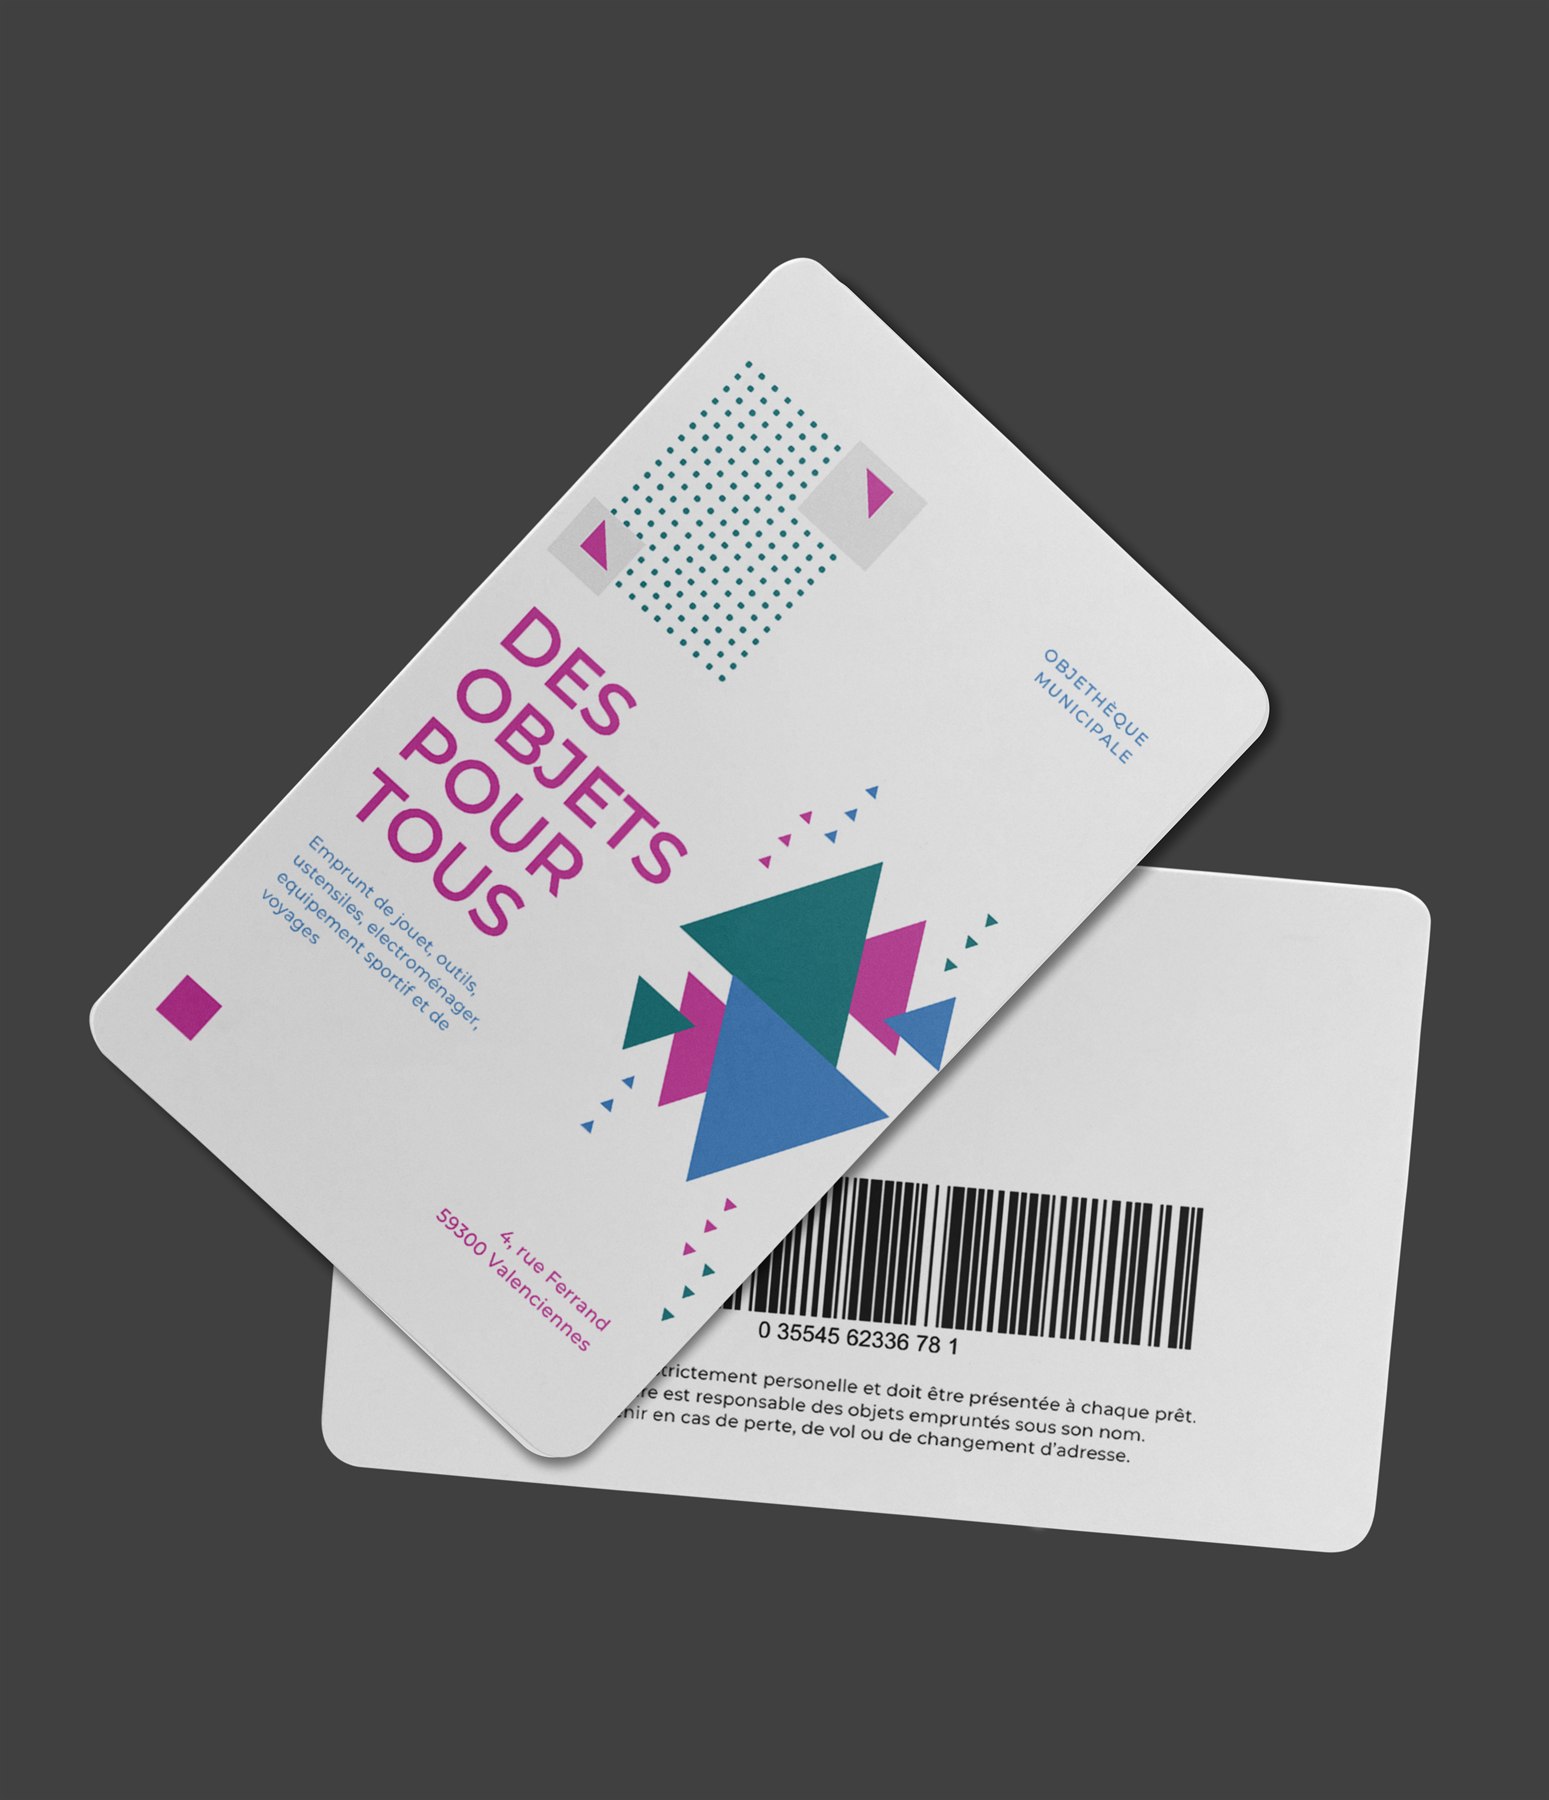
borrowing rather than buying has become a reflex.
every repair in the object's passport.
the impact of the purchase on the quota and offers to take back
the old appliance to bring it down: “One goes out, one comes in.”